Setting the scene: why this comparison matters now
The Philippines has seen a steady move toward quick online credit, and many Filipinos are choosing convenience over branch visits. That shift makes platforms like didi finanzas worth a clear-eyed comparison with other express loan options. Urban centres such as Metro Manila already show heavy uptake of app-based disbursement and instant onboarding, a trend backed by World Bank evidence of rising digital financial inclusion across Southeast Asia. The practical question now is which services give real value without hidden costs.
How express loans differ: features that change outcomes
Express lenders promise speed: instant underwriting, minimal KYC, and same-day disbursement. Those features help when cash is urgent, pero they also shift the trade-offs. Faster underwriting often means higher APR and shorter loan term, which raises monthly pressure. Look for clear statements of interest rate, credit score impact, and any origination fees before you accept a contract. These are not just buzzwords; they determine the total cost and repayment behavior.
DiDi’s approach versus typical alternatives
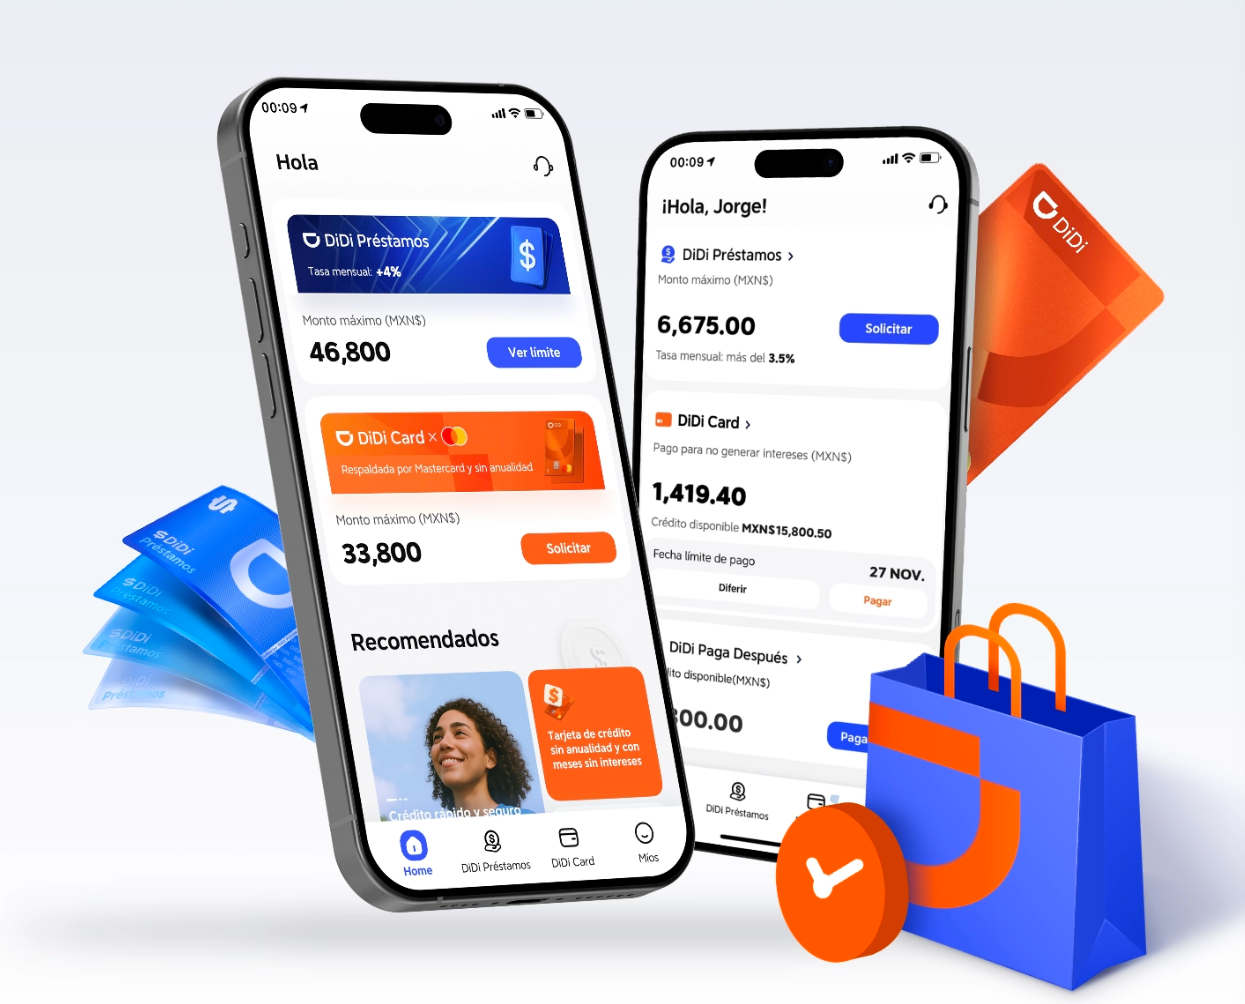
DiDi tends to position itself as a platform integrated with mobility and services, adding a layer of data sources for credit decisions. Competing apps focus pure-play lending—lean product design, aggressive approval, and streamlined KYC. The difference matters: platforms with richer transaction data can sometimes offer more tailored loan terms, while pure lenders win on speed and fewer steps. For everyday borrowers in provincial towns and city barangays, the choice often comes down to acceptable APR and realistic repayment schedules.
Trust, safety, and the real-world anchor
Trust is the pivot. In the Philippines, many users weigh reputation and reviews from local communities as heavily as formal disclosures. When assessing whether a platform is reliable, check publicly available customer service records and compliance cues—licences, data-protection statements, and transparent late-fee policies. For context: financial inclusion reports and central bank advisories in Manila have repeatedly highlighted borrower protection as a priority, which sets a benchmark for platforms claiming credibility. It helps to verify claims about reliability directly—see how didi finanzas es confiable is represented in customer feedback and policy documents.
Common mistakes borrowers make—and how to avoid them
Borrowers frequently accept the first offer, overlook total repayment, or miss the interaction between loan term and monthly cashflow. Another common error is assuming quick approval equals low cost—fast processing often carries higher interest. Practical steps: compare annualized interest rather than headline rates; confirm whether prepayment reduces interest; and read the small print on rollovers and penalties. If a lender pressures you to act immediately, that’s a red flag—step back and run the numbers.
Advisory: three golden rules for choosing fast online credit
1) Prioritise transparency over speed: pick lenders that disclose APR, fees, and the full repayment schedule up front. Clear disclosure reduces surprises and helps budgeting.
2) Match loan term to cashflow: choose a term that keeps monthly outflow manageable, even if it raises the nominal interest slightly. Short-term relief that strains future months is counterproductive.
3) Verify identity and complaint channels: confirm a lender’s KYC practices, customer support hours, and whether dispute resolution is local. Local accountability matters—especially outside Metro Manila.
Closing assessment and where DiDi fits
Choosing between DiDi-style offerings and pure-play express lenders comes down to three things: cost, clarity, and local accountability. When those align, borrowers get the speed they need without unnecessary expense. For many Filipino users, that alignment points toward platforms that balance mobile convenience with clear underwriting and fair repayment terms—precisely the value proposition you see reflected in reviews and policy notes around the region. DiDi Finanzas fits naturally into that mix as an option that aims to bridge service integration with accessible credit — reliable when its disclosures match practice. —